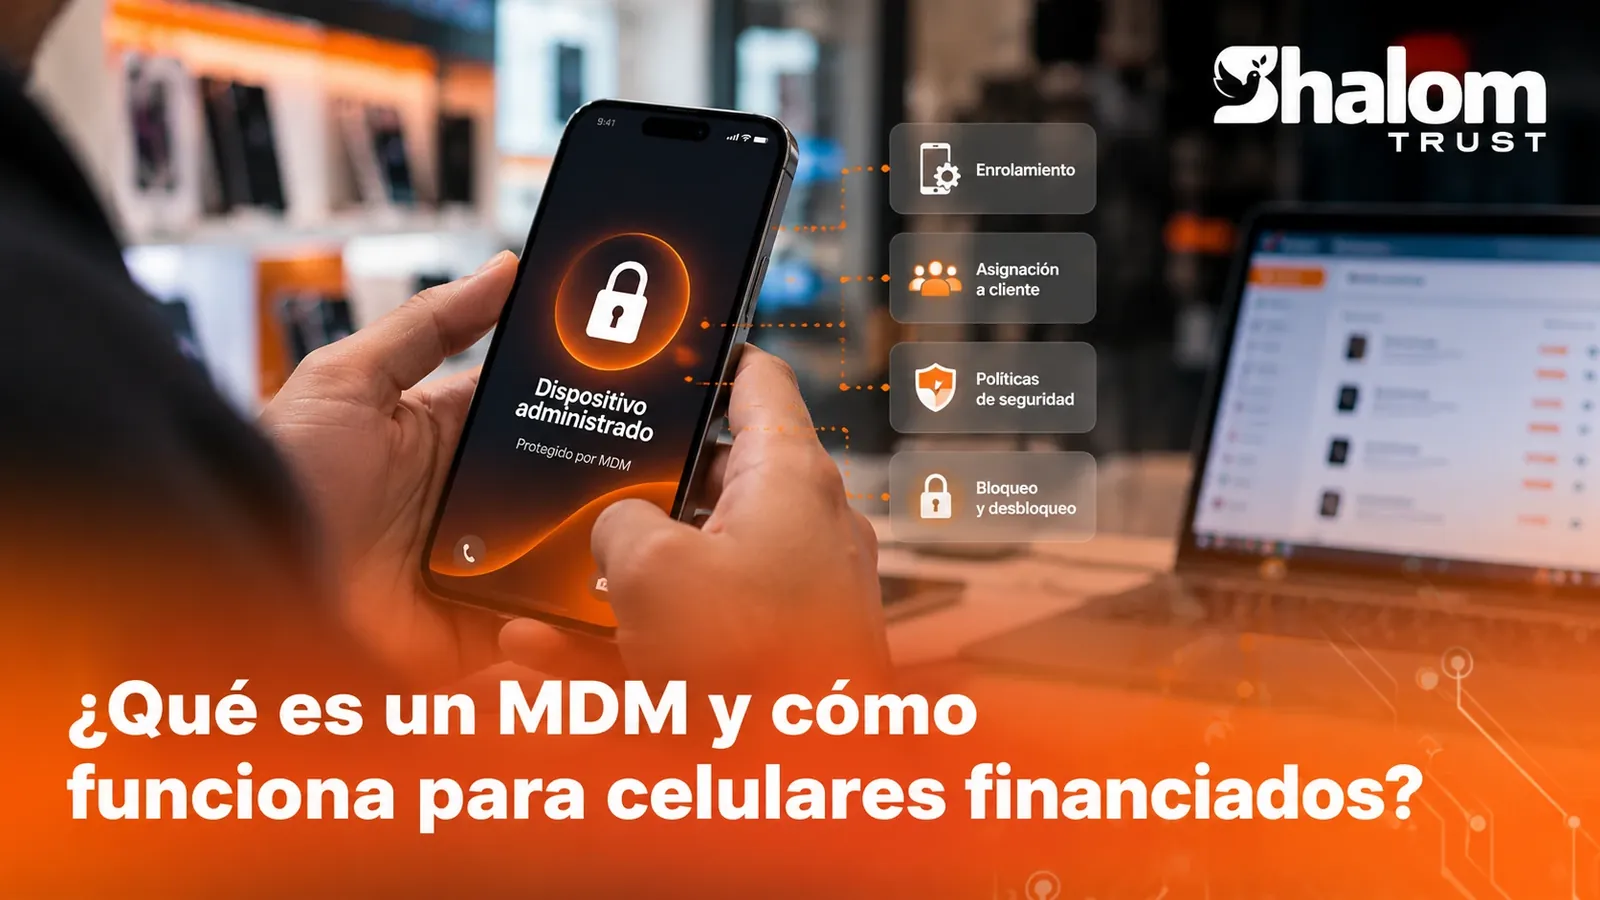
Financing iPhones as a line of business demands order. These are the pieces your operation should have and who should be in charge of each one.
Financing iPhones occasionally and doing it as a line of business are two different things. As soon as the portfolio grows, companies financing iPhones need an operation that works every day without depending on a single person.
This article describes the pieces of that operation from a business point of view: what each one is and who should be in charge of it. We cover day-to-day operations in how to manage iPhones sold on credit.
Summary: you need an MDM platform connected to your collections, a process for preparing each device, a clear contract, an organized inventory and a delinquency policy. Each piece has someone responsible for it.
The pieces of your operation
A platform connected to collections
This is the system from which you see your devices and take action on them. What makes the difference is that it is connected to customers, contracts and payments, so that each iPhone is tied to its credit.
A preparation process
Each iPhone is prepared in the store before delivery. With a guided process, your staff does it step by step and all branches work the same way.
A clear contract
The customer must know and accept in writing that the device will be managed for the duration of the credit, what happens if they fall behind and how it is released once they finish paying.
An organized inventory
Each iPhone is registered with its serial number and IMEI. That way you always know which device you have in store and which one corresponds to each contract.
A delinquency policy
Define in writing the days overdue, the prior notices and the hours allowed for taking action. This is what lets collections apply equally to all customers.
Who is in charge of what
| Piece | Suggested owner | Review |
|---|---|---|
| Choosing the platform | Management | As the portfolio grows |
| Device preparation | Branch | At each sale |
| Inventory | Inventory or branch | At each device intake |
| Delinquency policy | Credit and collections | Periodically |
| Device release | Administration | When each credit closes |
Costs and effort
When planning your operation, keep in mind:
- The MDM license, quoted according to the platform and the number of devices.
- The time of the staff who prepare and deliver the devices, which a guided process reduces.
- The purchase of the devices you are going to finance.
Checklist to get started
- You have an MDM platform connected to your collections.
- Your staff knows the preparation process.
- The contract explains device management.
- Each iPhone is registered with its serial number and IMEI.
- The delinquency policy is in writing.
- There is a procedure for releasing devices.
Frequently asked questions
Do I need my own server?
No. You work from your dashboard and the platform takes care of the rest.
Do I need a technical team?
No. Preparing each device is a guided process, designed for your store staff to follow.
Can I finance iPads as well as iPhones?
Yes. Remote lock and unlock work on iPhone and iPad.
How Shalom Trust solves it
With Shalom Trust you prepare each device with a step-by-step guide and, from your dashboard, you check managed devices and run their actions. Learn more in Apple MDM or request a demo.
Conclusion
Managing financed iPhones at scale is a matter of order: a connected platform, clear responsibilities and written processes. With those pieces in place, your credit operation does not depend on anyone's memory.