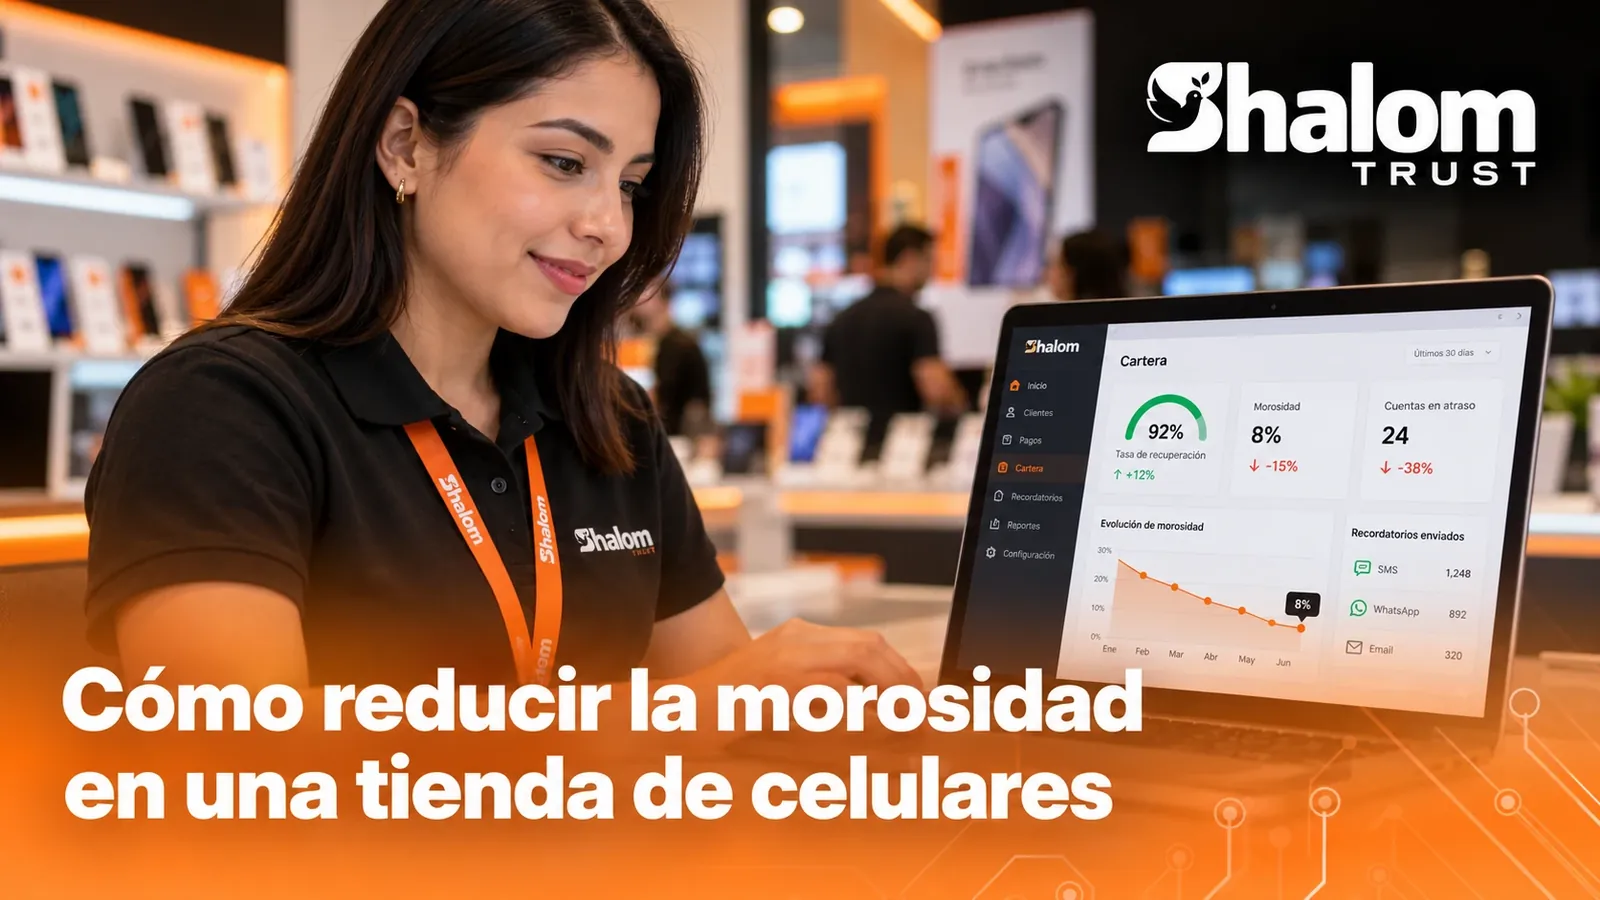
Delinquency is rarely solved on the day of the delay. It is prevented at the sale, detected early and managed with an orderly process. Here is how to organize it.
In a store that sells phones on credit, delinquency does not appear out of nowhere. It builds up from installments that do not fit the customer's income, reminders that never arrive, delays nobody looks at in time and agreements that get forgotten. The good news is that nearly all of these points can be put in order with a clear process.
Start before you sell
Installments the customer can pay
The most effective way to avoid delinquency is not to create it. Before approving a sale, compare the installment amount with what the customer can realistically pay. A payment plan adjusted to their capacity is better business than a shorter one that ends up overdue.
Frequency aligned with their income
If the customer is paid every week, a weekly installment feels more natural than a higher monthly one. Offering weekly, biweekly or monthly frequencies according to how they receive their income reduces forgotten payments and cash shortfalls.
Down payment
A down payment commits the customer from day one and reduces the balance at risk. Define a consistent policy: what percentage you ask for, on which devices and in which cases you make exceptions.
Complete data from the start
Many delinquency cases become difficult because there is no way to reach the customer. Record their contact details and a reference carefully, and confirm them at the time of sale.
Reminders that arrive on time
A reminder sent before the due date prevents more delays than ten calls afterward. A simple sequence could be:
- A notice a few days before the due date.
- A reminder on the day itself.
- A follow-up if the payment was not recorded by the next day.
Organize the portfolio by aging bucket
Not all delays need the same response. Grouping the portfolio by days overdue lets you decide who to call first and with what message. Each business defines its own buckets; one way to organize them could be:
| Bucket | Situation | Suggested action |
|---|---|---|
| Current | No overdue installments | Preventive reminders |
| Early delay | A few days past the due date | Friendly reminder and payment options |
| Mid-stage delay | The customer did not respond to first contact | Personal call and agreement proposal |
| Advanced delay | Several unpaid installments | Priority handling and application of the agreed policy |
Reviewing this list every day, rather than at the end of the month, is what lets you act while things are still easy to resolve.
Payment promises: record them and follow through
When a customer says "I'll pay on Friday", that is valuable information. Record it with the promised date and amount, and follow up on that day. A promise nobody checks is a missed opportunity; a promise that is monitored tends to be kept.
One history per customer
Whoever calls an overdue customer should have in view, in one place:
- Their contract and installment plan.
- Payments made and payments pending.
- Previous payment promises and whether they were kept.
- The linked device and its status.
With that information, the conversation is shorter, fairer and more effective. Without it, every call starts from scratch.
Make paying easy
Every obstacle to paying is a reason to fall behind. Offer the payment methods your customers actually use and record each payment as soon as it is received, so that the customer's balance and status are always up to date.
When the delay persists
If the customer does not respond to reminders or agreement proposals, the policy both parties signed applies. In selling phones on credit, that policy can include managing the device through an MDM. We explain this in how locking phones for non-payment works.
Measure to improve
You do not need complicated reports to get started. Regularly check how many customers are current, how many are in each aging bucket and how many payment promises were kept. Those numbers, specific to your business, will tell you which part of the process to adjust.
A daily collections routine
Consistency beats intensity. A short routine, every day at the same time, usually gives better results than a long day of calls at the end of the month:
- Review the payments received since yesterday and confirm they are recorded.
- Look at the payment promises due today and contact those who did not keep them.
- Go through the aging buckets from lowest to highest: recent delays are the easiest to resolve.
- Record every contact: what was discussed, what was agreed and when the next step is due.
- Escalate what is not moving according to the policy: more days overdue, another person or the next agreed step.
What to say at each contact
Short, concrete messages work best. These are examples of tone that you can adapt to your business and channels:
- Before the due date: "Hi, a reminder that your installment is due on Friday. You can pay in store or by transfer. Thank you!"
- On the due date: "Your installment is due today. If you have already paid, please ignore this message."
- First delay: "We noticed your installment is pending. Can we help you find a date to catch up?"
- After a broken promise: "On Friday we agreed on a payment that was not recorded. Can we talk today to see how to sort it out?"
Notice what they have in common: they say what is happening, offer a way out and do not threaten. And if the customer replies, the conversation moves to a person.
Payment agreements without losing control
Sometimes the customer wants to pay but cannot do so as planned. A well-made agreement recovers both the payment and the relationship:
- In writing: date, amount and payment method for each new commitment.
- Realistic: a small agreement that is kept is better than a large one that is broken.
- With follow-up: each commitment in the agreement is a payment promise reviewed on its date.
- With limits: define in your policy how many agreements are allowed per customer and who can approve them.
Mistakes that increase delinquency
- Collecting only at the end of the month. By the time you check, the delay is already several weeks old.
- Recording payments late. A customer who paid and gets a complaint loses trust; one who did not pay and gets no contact loses urgency.
- Treating all delays the same. One day overdue does not deserve the same message as a month.
- Relying on the salesperson's memory. If the information lives in a notebook or a personal chat, it is lost when that person is away.
- Not closing the loop. Customers who finish paying deserve a confirmation and, in the case of phones, the release of the device.
Frequently asked questions
How often should reminders be sent?
Just enough so the customer does not forget, without overwhelming them. A sequence before the due date, on the due date and shortly after is usually enough. Adjust the frequency according to how your customers respond.
Should you charge late fees?
It depends on your policy and, above all, on what the law in your country allows. If you apply them, they must be in the contract and explained at the sale.
What do I do with a customer who does not respond?
Follow the agreed policy: contact through the registered channels, the reference they left and, if the contract provides for it, measures on the device. Record every attempt.
When is a debt written off?
Each business defines when a credit moves to written-off portfolio, using accounting and legal criteria. What matters is that the decision is explicit and recorded, rather than the debt simply being forgotten.
In short
Reducing delinquency is a sum of habits: selling with reasonable installments, reminding on time, prioritizing by bucket, following through on payment promises and keeping all customer information in one place. To see how we organize portfolio, payments and promises on a single platform, check out the Shalom Trust collections system.