Financing the phones you sell yourself can open you up to more customers, but it demands a clear process from start to finish. We review contract, schedule, risks and operations.
Many customers want a new phone but cannot pay for it in cash. Offering your own installment financing lets you serve that public without depending on a bank or a finance company. In exchange, the store takes on a new role: it no longer just sells devices, it also manages credit. This guide covers what you should have sorted out before starting.
1. Define your credit policy
The policy is the set of rules you will apply to all customers. Writing it down avoids improvised decisions at the counter:
- Requirements: what documents you ask for and how you verify identity and contact details.
- Down payment: whether you require one and how much, perhaps different according to the device's value.
- Terms and frequencies: how many installments you offer and how often (weekly, biweekly or monthly).
- Limits: maximum amount financed per customer and how many active credits they can hold at once.
- Delays: what happens at each stage of delay and what fees, if any, the law allows.
2. A clear contract
The contract protects both parties. It should set out in writing, in language the customer understands:
- The customer's and device's details, including its identifier.
- The total price, the down payment, the number of installments, their value and their dates.
- Late fees, if any and if the law allows them.
- That the device is managed through an MDM for the duration of the credit, what actions can be applied if the customer does not pay and how they are reversed.
- How and when the device is released once fully paid.
- The channels for paying and for contacting the store.
A signature, physical or electronic, and a copy for the customer complete the process.
3. The payment schedule
Every sale generates a schedule: a list of installments with their amounts and dates. That schedule is the basis of everything else, because reminders, balances and the customer's status all come from it. Building it by hand in a spreadsheet works with few customers, but it becomes fragile as sales grow. Ideally, each recorded payment should automatically update the outstanding balance and the next installment.
4. Know the risks
Financing means taking on risks that do not exist in cash sales. Keeping them in mind lets you prepare:
| Risk | What it involves | How to mitigate it |
|---|---|---|
| Non-payment | The customer stops paying installments | Tailored installments, reminders and early follow-up |
| Identity fraud | Someone buys with another person's data | Verify documents and contact details at the sale |
| Device loss | The device is lost or stolen | Clear policies in the contract and MDM management |
| Liquidity | The money comes in as installments, not all at once | Calculate how much capital you can allocate to credit |
| Operational disorder | Unrecorded payments, scattered data | A single system for customers, installments and payments |
5. Protect the device from delivery
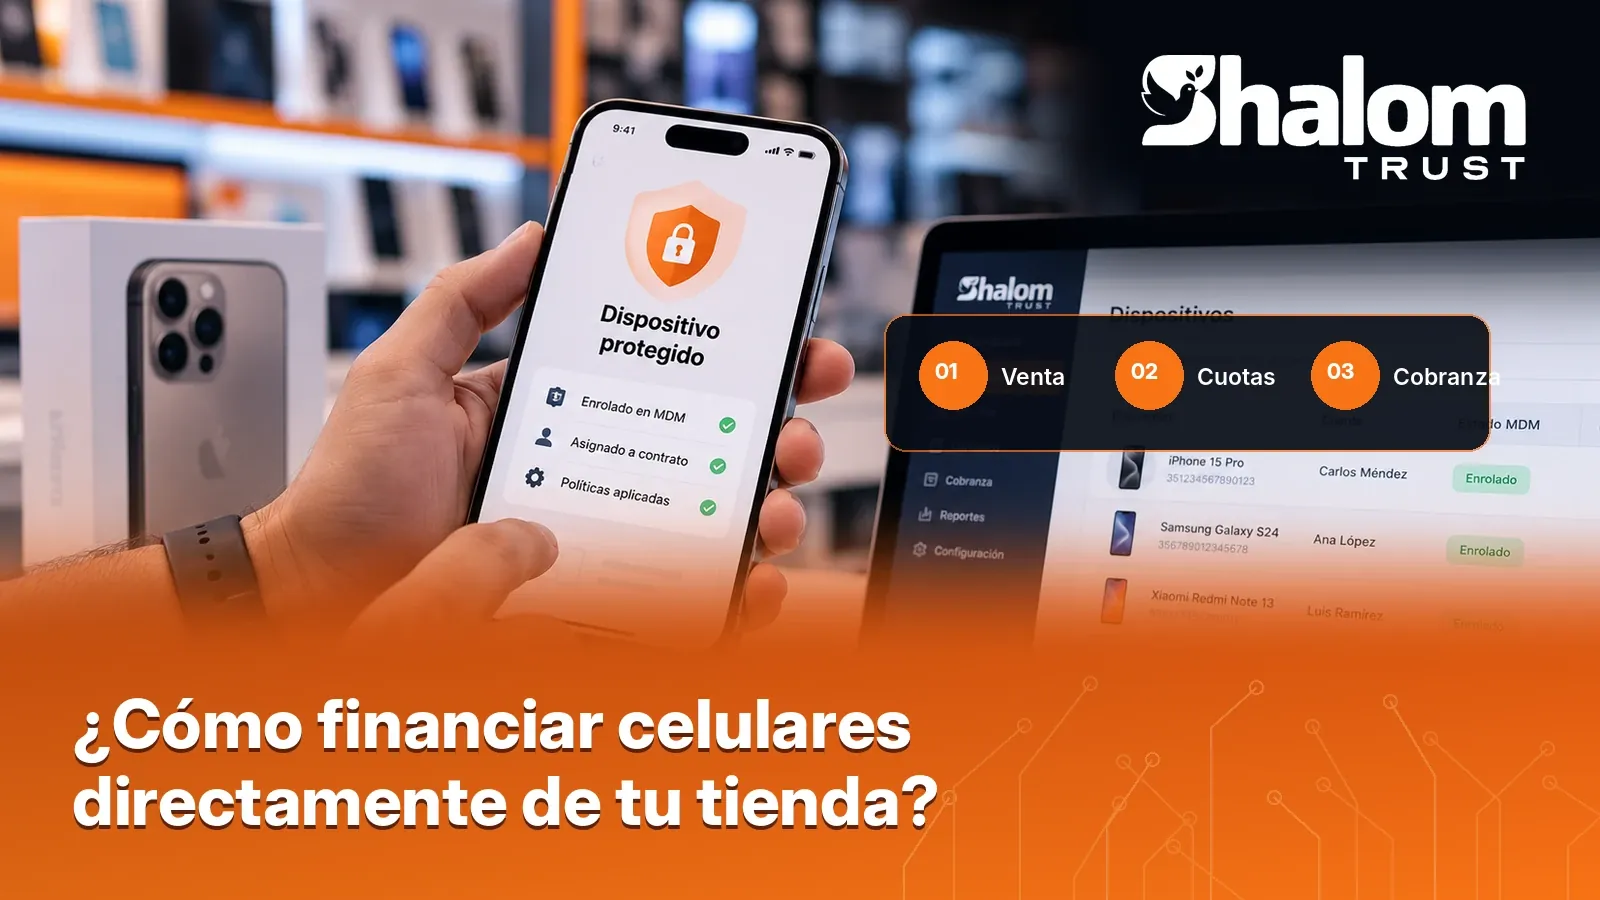
When selling phones on credit, the device itself is part of the collateral. That is why, before handing it over, you should enroll it in an MDM and link it to the customer's contract. That way, if the credit becomes delinquent, the store can apply the agreed actions, and once it is paid off the store can release the device. To understand how it works, start with what an MDM is and how it works for financed phones.
6. Day-to-day operations
An orderly financing program always follows the same path:
- Application: the customer provides their data and documents.
- Evaluation: the store applies its policy and decides.
- Contract and down payment: it is signed and the down payment, if any, is collected.
- Device preparation: enrollment in the MDM and link to the contract.
- Delivery: the customer takes the device and their copy of the contract.
- Collections: reminders, payment recording and follow-up on delays.
- Closure: when the last installment is paid, the device is released and the credit is closed.
Every step that gets recorded is one less problem when something goes wrong.
7. Start small and adjust
There is no need to launch the program in all branches at once. Starting with a group of devices and customers lets you adjust the policy, the terms and the collections process with your own data before growing. For the follow-up side, you will find how to reduce delinquency in a phone store useful.
How to calculate the installment
The basic calculation is simple, although each business decides whether and how to apply interest or fees, always within what the law allows. Without interest, the math is:
- Device price minus the down payment = amount financed.
- Amount financed divided by the number of installments = value of each installment.
For example, with round numbers and no interest: if a device costs 300 and the customer makes a down payment of 60, the amount financed is 240; over 12 monthly installments, each would be 20. Paid in biweekly installments over the same period, it would be 24 installments of 10. These figures only illustrate the math; they are not a recommendation on prices or terms.
What data to record at each sale
A well-documented credit is easier to collect and leads to fewer disputes. At each sale you should record:
- Customer: full name, ID document, phone, address and a contact reference.
- Device: brand, model and identifier (IMEI or serial number).
- Conditions: price, down payment, number of installments, frequency, dates and fees, if any.
- Contract: the signed version and the date of signing.
- Device management: that it was enrolled in the MDM and linked to the contract.
- Person responsible: who made the sale and who approved the credit.
Indicators to track the program
You do not need a complex dashboard to know whether the program is going well. With these indicators, calculated from your own data, you get a clear picture:
- Current portfolio: what share of active credits has no overdue installments.
- Portfolio by aging bucket: how many customers are in each bucket and how that changes week by week.
- Payment promises kept: of the promises recorded, how many were kept.
- Closed credits: how many customers finished paying and whether their devices were released.
- Committed capital: how much money you have tied up in devices still being paid for.
Review them as often as you make decisions: if you adjust the policy every month, look at the indicators every month.
Frequently asked questions
Do I need a license to sell on credit?
It depends on the country. In some, offering consumer credit requires registration or authorization and is subject to rules on interest and contracts. Consult a legal advisor before launching the program.
Can I finance used devices?
Yes, with the same rules, but first check that the device can be enrolled in your MDM: that it is free of its previous owner's accounts and that the model is in your confirmed catalog.
What happens if the customer wants to pay early?
Define in the policy whether it is allowed and how the balance is recalculated. A system that records each payment against the installment schedule handles this without manual calculations.
What do I do with the contract when the customer finishes paying?
Mark the credit as closed, confirm to the customer that there is no outstanding balance and release the device from the MDM. Keep the contract and the history for as long as the law requires.
In short
Financing phones from your store is viable if you treat it as what it is: a credit business. You need a written policy, a clear contract, a reliable payment schedule, awareness of the risks and a process that starts before handing over the device and ends when it is released. If you want to manage customers, contracts, installments and payments on a single platform connected to the MDM, explore the Shalom Trust collections system or check out our plans.